

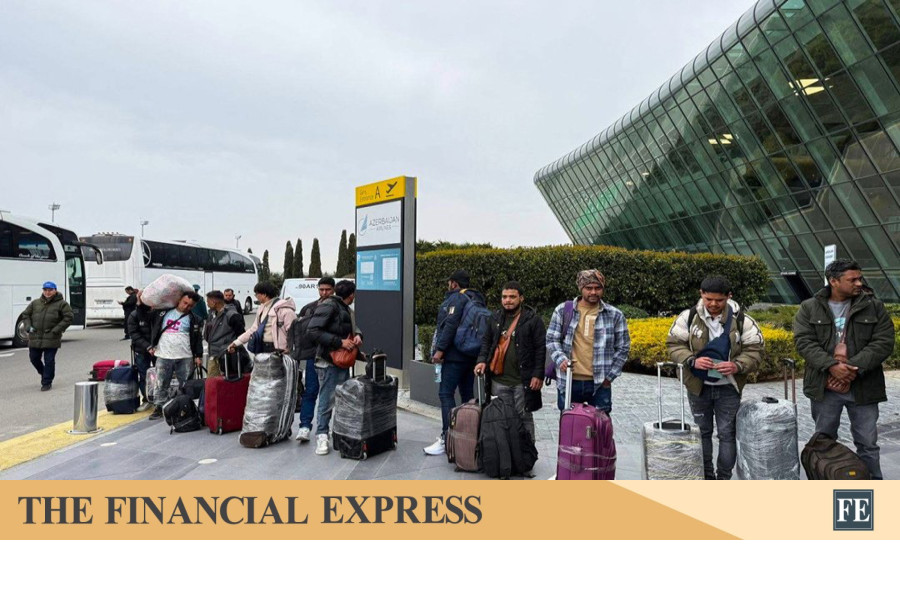
In recent public forums and news outlets, some prominent personalities have asked: why do young Bangladeshis spend family savings, borrow heavily, or sell inherited assets to secure employment abroad rather than invest those resources in domestic enterprises that could generate income and create jobs? The question deserves serious economic examination. The answer lies less in the availability of capital than in the institutional environment that determines its expected returns and risks. Households are not misjudging their options; they are reading the incentives correctly. The failure lies in the institutions that shape those incentives.

PRIVATE RATIONALITY, SOCIAL COST: Economics distinguishes between private and social returns. A household choosing between financing overseas employment and starting a business considers its own income, costs, and risks. Society has a further interest in the jobs, local purchases, and demand that a successful enterprise generates. Those wider benefits may exceed the owner’s profit, yet the owner cannot capture them. Migration, too, yields benefits beyond the household: remittances, foreign exchange, and skills. The question, then, is not whether enterprise is always socially superior, but whether institutional distortions discourage enterprises whose social benefits exceed their private rewards.
This gap explains an apparent paradox: what is rational for the household may fall short of what is best for the nation. The remedy is not to condemn household decisions but to change the conditions under which they are made, so that private incentives and social benefits point in the same direction.
RISK-ADJUSTED RETURNS & OPPORTUNITY COST: Both paths involve uncertainty, but of different kinds. A migrant’s earnings can be estimated from wages, living expenses, recruitment costs, and the length of employment, though recruitment may fail, contracts may go unfulfilled and months may be lost. An entrepreneur must estimate uncertain sales, operating costs, financing charges, and the chance of failure. Even when expected business profits are higher, the risk of losing the family’s accumulated savings can make migration the better choice.
Opportunity cost sharpens the comparison. Money committed to one option cannot finance the other, and months spent building a customer base are months without alternative earnings, while rent, utilities, and loan installments fall due immediately. The relevant comparison is therefore between expected risk-adjusted net returns, including the cost of failure, and not between the sums spent on each path.
SIX TRAPS, ONE ENTREPRENEURIAL PENALTY: Six interlocking economic traps tilt that comparison toward migration for work. Although they operate through different channels, their cumulative effects create a self-reinforcing Poverty Loop that penalises domestic entrepreneurship.
The Political Confrontation Trap creates uncertainty over policy, transport, and commercial activity. The Corruption Trap distorts access to licenses, credit, and public services, rewarding connections over merit. The Extortion Trap raises production, transportation, and distribution costs through payments businesses cannot avoid. These operate as an unofficial tax on enterprise, but unlike a statutory tax, its size and timing cannot be budgeted. The traps also feed one another: political uncertainty weakens enforcement, which lets corruption and extortion flourish, and extortion in turn erodes profitability and reinvestment. The result is an entrepreneurial penalty: a productive investment must earn enough to cover not only legitimate costs but also institutional risks that should not exist.
The fourth, the Capital Flight Trap, works through the exchange rate. Illicit transfers abroad drain domestic capital accumulation and add to demand for foreign currency, which, unless offset by other inflows, pushes the taka down. Depreciation raises the taka cost of imported machinery, energy, and raw materials, making domestic enterprise more expensive, while raising the taka value of foreign earnings and strengthening the pull to migrate. However, higher nominal earnings in taka do not necessarily translate into greater real purchasing power, since depreciation can fuel domestic inflation. The incentive to migrate may nevertheless strengthen when the expected real returns from overseas employment exceed the increasingly uncertain returns from domestic entrepreneurship.
The fifth is the High Inflation-High Interest Rate Trap. Political disruption, corruption, extortion, and depreciation raise costs that firms pass on to consumers. Persistent inflation invites tight monetary policy, and banks facing higher funding costs and default risk raise lending rates or ration credit. Entrepreneurs then face dear inputs, dear finance, and customers whose purchasing power is shrinking.
Banking distress deepens the problem. The World Bank reported in October 2026 that non-performing loans reached 33.2 percent of total loans in June, a sign of deep weakness in credit allocation. A capable entrepreneur without collateral or connections may be denied finance even when the business is sound.
The sixth is the Poverty Trap. Costly credit and uncertainty suppress investment; weak investment limits jobs and incomes; stagnant incomes weaken demand; and weak demand discourages new enterprise. Poverty feeds back into the cycle, because poor households cannot absorb business losses, pay for training, or seek legal remedy against extortion. Their children inherit not only limited savings but narrower opportunities. Poverty is thus both an outcome of weak entrepreneurship and a cause of its persistence.
Together these form a self-reinforcing Six-Trap Poverty Loop. Within it, migration becomes a strategy for escaping domestic risk, not necessarily a preference for living abroad, and it can look more attractive than enterprise even when enterprise might serve the nation better.
MIGRATION IS NOT CAPITAL LOST: Not all migration spending represents a loss to Bangladesh. Some circulates domestically, while remittances finance consumption, education, health care, housing, and investment, besides supplying foreign exchange for imports and external obligations. Returning migrants may establish businesses using their savings, acquired skills, and international experience. Thus, migration generates economic benefits that flow back home, although often with a delay and through indirect channels. These benefits, however, do not necessarily substitute for the employment, production, and local supply chains that a viable domestic enterprise can generate. Neither option is universally superior; their relative social returns depend on productivity, employment creation, remittances, risks, and the opportunity costs of alternative uses of resources.
Nor can every prospective migrant be presumed capable of becoming an entrepreneur. Entrepreneurship requires managerial ability, market knowledge, technical skills, risk tolerance, and sufficient demand for the products or services offered. Redirecting family savings toward enterprises without these prerequisites could expose vulnerable households to greater financial losses. The objective, therefore, is not to discourage migration but to remove the institutional and economic disadvantages that prevent domestic entrepreneurship from becoming a genuinely competitive alternative.
MAKING THE INCENTIVES CONVERGE: Breaking the Poverty Loop requires more than identifying the traps that discourage domestic entrepreneurship. It requires policies that systematically reduce the entrepreneurial penalty and make investment at home economically attractive. Affordable registration, transparent licensing, simplified taxes, enforceable contracts, protection from extortion, and prompt resolution of commercial disputes would lower the costs and risks of starting a business. Bank lending should follow commercial viability and repayment capacity rather than political influence, while accessible working-capital loans, reliable infrastructure, technical training, and market access would improve the prospects of first-time entrepreneurs.
However, the effectiveness of these reforms ultimately depends on institutional credibility and consistent enforcement. One-stop registration accomplishes little if unofficial payments remain unavoidable, while subsidised loans cannot sustain businesses squeezed by extortion and weak demand. Similarly, credible monetary management can help contain inflation, but it cannot independently repair institutional dysfunction. Efforts to curb illicit capital flight, strengthen banking governance, and stabilise foreign-exchange conditions must therefore complement broader institutional reforms.
Ultimately, the objective should not be to favour migration over entrepreneurship, or entrepreneurship over migration, but to create an economic environment in which individuals can make choices based on genuine opportunities rather than institutional distortions. Overseas employment, salaried work at home, and self-employment should all remain viable and dignified options for Bangladeshis. Appeals to patriotism cannot substitute for economic incentives, and families should not be asked to sacrifice their security for benefits that accrue to others. The challenge is to make investing family capital at home profitable, predictable, and safe. Until the Poverty Loop is broken, urging prospective migrants to redirect their savings will not change their economic calculations. Capital follows opportunity, and opportunity depends on institutions. Rebuilding those institutions is the bridge between household rationality and national prosperity.
