

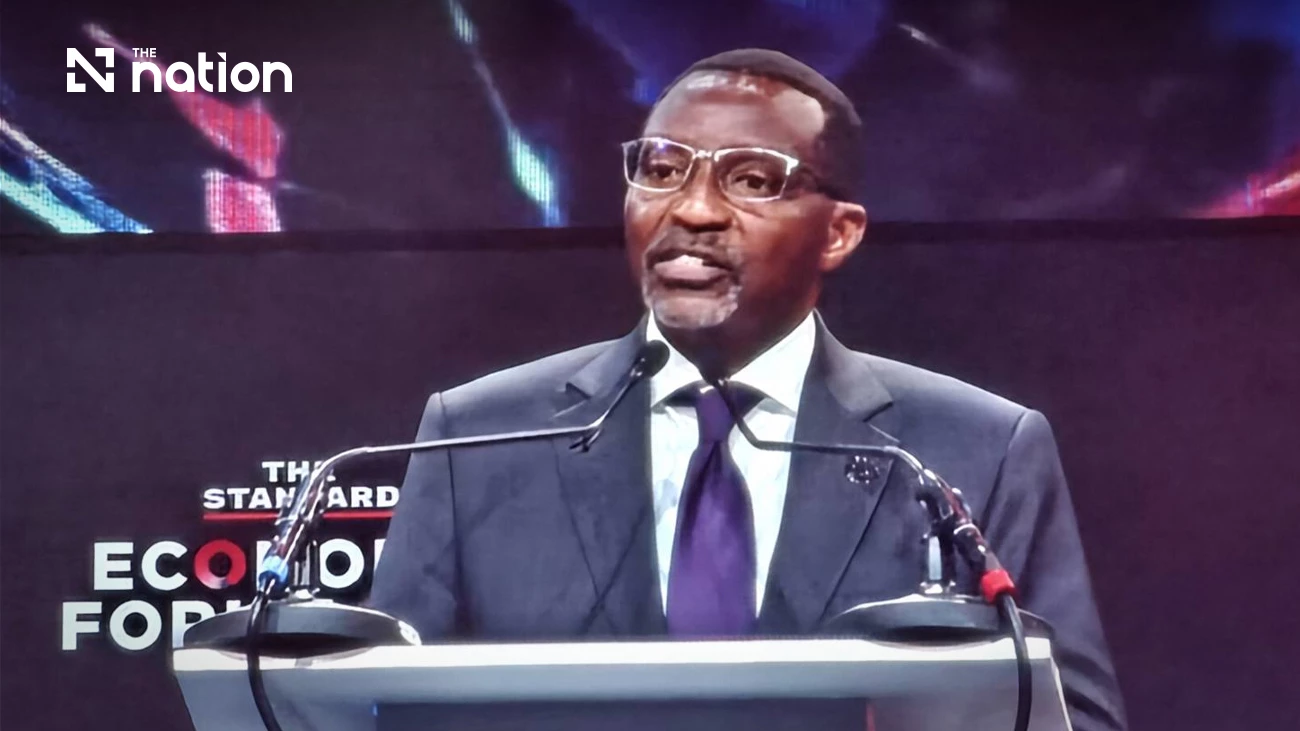
Stephen Ndegwa tells The Standard forum that business dynamism, AI adoption among small firms and deeper ASEAN integration could put high income within reach
- The World Bank’s plan aims to reignite Thailand’s <a href="https://bitcomme.com/why-productivity-gains-are-only-the-beginning-2/” title=”why productivity gains are only the beginning”>productivity to help it achieve high-income status by 2037.
- The first step is to increase business dynamism by lowering entry barriers for new firms, strengthening competition, and improving access to finance for SMEs.
- A second key step is to promote the widespread adoption of practical and affordable artificial intelligence (‘small AI’) among small firms and farms.
- The third step involves deepening economic integration, particularly within the ASEAN region, by reducing trade barriers and helping more SMEs join export supply chains.
- This strategy is a response to Thailand’s slowing economic growth and fading productivity since the pandemic, which jeopardizes its long-term goals.
Thailand can reach high-income status by 2037 only if it restores the productivity that once powered its economy, and the World Bank has set out three concrete opportunities to do so: more dynamic businesses, wider use of artificial intelligence among small firms, and deeper integration with ASEAN.
Stephen N. Ndegwa, the World Bank’s division director for Thailand and Myanmar, delivered the keynote at the opening of “Economic Forum 2026: Reinvent Thailand”, hosted by The Standard.
His speech, titled “Building Thailand’s Future Today: Higher Value, Better Jobs”, drew lessons from the recent IMF–World Bank annual meetings in Bangkok.
“If Thailand can reignite its productivity, it can return to faster growth and put high income within reach,” Ndegwa said.
He described the meetings, which drew nearly 20,000 participants, as perhaps the most successful held outside Washington and said they allowed Thailand to showcase 35 years of development.
The growth gap
Ndegwa said growth averaged about 8% in the 1990s, driven largely by investment in physical capital, which accounted for around three-quarters of expansion.
After the Asian financial crisis, productivity took the lead. Since the pandemic, however, growth has slowed to about 2.2% a year, and productivity’s contribution has also faded.
To become a high-income country by 2037, per capita income growth must be at least 5.4% a year, he said. At the current pace, the goal would not be reached until 2206.
With the workforce shrinking because of demographic change, making every worker and every part of the economy more productive is the only route, he argued. Using the football metaphor heard throughout the day, he likened productivity to the formation a team needs to win: Thailand has the players but must arrange them to get the most from each.
Opportunity one: business dynamism
The first priority is to lower entry barriers and encourage competition. New firms in Thailand rose from about 0.9 per thousand working-age people in 2008 to 1.7 in 2024, which he called the right direction, but high-income economies see about 7.5. Scale is another weakness.
Micro firms make up about 81% of Thai manufacturers but provide only about 16% of manufacturing jobs, and small firms generate less than half the value added per worker of medium and large ones.
“If we don’t allow and promote and energise small firms to grow, we will not get the kind of jobs that we need,” he said.
Drawing on a World Bank flagship report launched about a month ago, he recommended four actions, some of which the government is already pursuing: Cut the cost of starting and scaling up by completing the regulatory “guillotine” and letting tax preferences taper as firms grow.
Strengthen competition by levelling the playing field between state-owned enterprises and private companies and by monitoring mergers and acquisitions to prevent market dominance.
Offer incentives to help small and medium-sized enterprises (SMEs) become more productive, but make them time-bound and measured against results. Widen SME access to finance. About 40% of small firms have a bank loan, compared with 60% of medium-sized firms.
Firms without collateral could qualify through digital transaction data showing turnover, customer base and sound account management.
Opportunity two: ‘small AI’
The second opportunity is for Thailand to ride the AI wave. The country has attracted data centres successfully, Ndegwa said, but the biggest gains will come from practical, affordable tools used widely by farms and workers.
“Small AI can bring a big job advantage to Thailand,” he said.
The gap is wide. Some 12% of Thai farms use AI, against 43% in the United States, and only 7% of small firms do, compared with 33% in the US. Doubling or tripling that share would be a significant gain. Adoption is higher among younger firms, exporters and more productive companies.
He sought to ease fears over job losses, saying World Bank research shows Thai firms expect employment to rise, not fall, alongside higher productivity.
On innovation, only 8% of Thai firms have introduced a process innovation or quality certification. He urged policymakers to reorient data-centre policy towards encouraging AI adoption among small businesses.
Opportunity three: deeper integration
Thailand’s prosperity, Ndegwa said, owes much to early and consistent openness, but this now needs to deepen and become more efficient. That means bringing more SMEs into export supply chains. Exporting firms tend to be more productive and pay at least 10% more in wages.
ASEAN, a market of more than 700 million people on Thailand’s doorstep, is the natural place to start. Intra-ASEAN trade accounts for only about one-fifth of the region’s trade, compared with two-thirds within the European Union.
He called for advancing trade facilitation and regulatory cooperation and cutting non-tariff barriers.
Private capital
Ndegwa also highlighted private capital mobilisation. No country has enough public capital to fund the growth it needs, he said, and the private sector is the main engine of job creation.
Thai investment of 22% of GDP, which Deputy Prime Minister Ekniti Nitithanprapas also cited earlier, is reasonable but well short of the roughly 30% average for upper middle-income countries.
A credible promise
Concluding, Ndegwa said the World Bank believes the agenda is achievable.
Thailand has strong, resilient fundamentals and has made such a leap before, he said, and there is clarity of ambition between government and the private sector, as well as a “hunger for jobs and expansion” among the population.
“We think this is a credible promise,”he said, with a credible set of actions that could take Thailand to high income within the next 12 years.
