

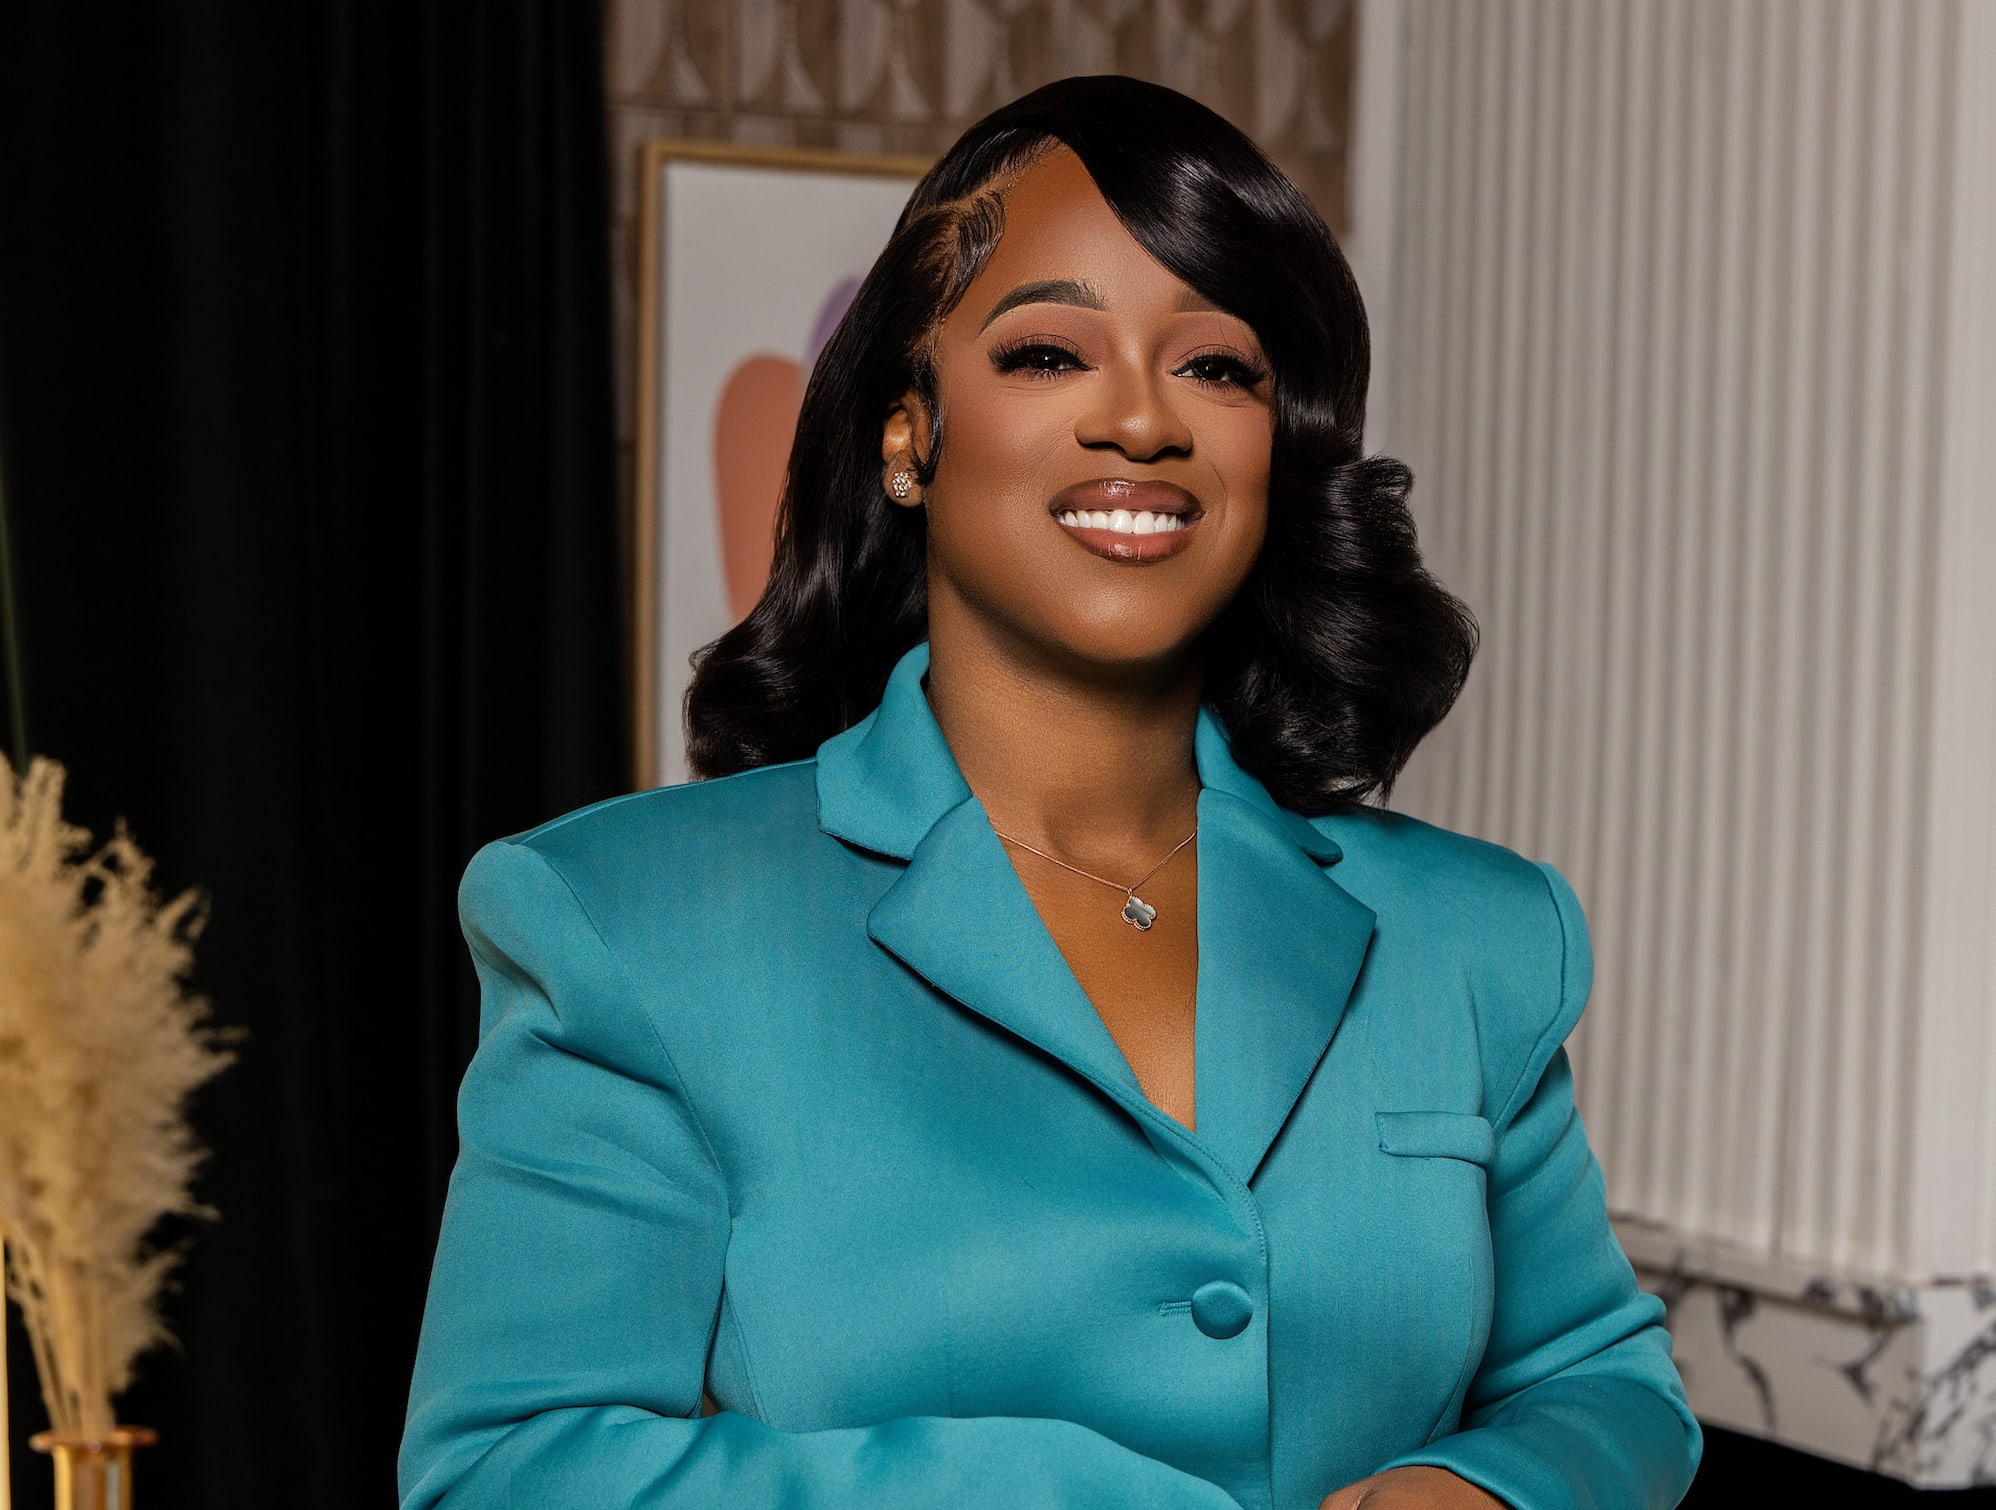
Dallas financial services entrepreneur Nicole Washington shares hard-earned lessons on business credit, tax planning, managing debt and building lasting wealth.
ByCrystal WillisPublished about an hour ago•4 min read

Nicole Washington, founder and CEO of Revised Financial Services and Revised Tax Software
As 2026 comes to a close, women entrepreneurs are setting bigger revenue goals, planning new ventures and preparing for another year of growth. But before updating the vision board or manifesting the next million, there’s an important question worth asking: Is your business financially prepared for the success you’re working toward?
For Dallas-based entrepreneur Nicole Washington, founder and CEO of Revised Financial Services and Revised Tax Software, financial freedom requires more than earning a substantial income. With 11 years of experience in the tax and credit industry, Washington has built her businesses while navigating single motherhood, financial setbacks and the realities of entrepreneurship.
Her journey began with a résumé-writing business before expanding into credit services, tax software and mentorship. Along the way, she discovered that making money and managing it responsibly are two entirely different skills. In a recent interview, Washington reflected on the financial lessons that changed her approach to entrepreneurship and offered insights that women business owners can apply as they prepare for 2027.
1. Stop Confusing Revenue With Wealth
Generating six or seven figures in revenue doesn’t automatically mean you’re financially secure. Washington learned this firsthand after experiencing significant business growth and increasing her personal and professional expenses, including purchasing luxury vehicles and expanding her operations.
“Even though I could afford it at the time, it was the longevity of affording it that I wasn’t taking into consideration,” Washington explained.
Her experience highlights the importance of evaluating profitability, recurring expenses and long-term financial obligations before making major purchases. A successful business should generate more than impressive revenue numbers; it should provide sustainable financial stability.
2. Get Serious About Your Credit Before You Need Funding
For entrepreneurs planning to expand, personal credit can significantly influence financing opportunities, particularly when lenders require personal guarantees. Washington, whose passion for credit improvement helped shape her financial services career, encourages business owners to monitor their credit consistently rather than waiting until they need a loan.
Reviewing credit reports, addressing inaccuracies and maintaining responsible payment habits are important steps toward financial readiness. Entrepreneurs should also understand how existing debt and credit utilization may influence lending decisions.
3. Make Tax Planning a Year-Round Priority
Tax season shouldn’t be the first time entrepreneurs examine their financial records. Through Revised Tax Software, Washington mentors aspiring tax professionals and works with entrepreneurs navigating business financial responsibilities.
Before year-end, business owners should organize receipts, reconcile accounts, review estimated tax obligations and evaluate whether their business structure still supports their financial goals. Consulting a qualified tax professional can help identify potential issues and ensure financial decisions align with current tax requirements.
4. Avoid Taking On More Debt Than You Can Sustain
As entrepreneurs grow, access to financing can create opportunities for expansion. However, Washington cautions against making financial commitments based solely on anticipated income.
“Don’t bite off more than you can chew,” she advised, reflecting on her own experiences managing business expenses and unexpected financial setbacks.
Before financing equipment, expanding operations or purchasing expensive assets, entrepreneurs should evaluate repayment obligations and consider whether those expenses remain manageable during slower business periods.
5. Schedule Quarterly Financial Check-Ins
One of Washington’s biggest lessons from entrepreneurship is the value of financial accountability. She recommends having an accountability partner or financial planner who can periodically review spending decisions, business goals and financial responsibilities.
Quarterly financial reviews can help entrepreneurs monitor profitability, identify unnecessary expenses and adjust their strategies before financial challenges become overwhelming. Regular check-ins also create opportunities to make more intentional decisions about investments and future growth.
6. Build Better Systems Before Launching Another Business
Entrepreneurship often promises flexibility and independence, but Washington discovered that freedom requires structure. During her early years in credit services, client files filled her workspace while growing professional responsibilities disrupted her family routines.
Over time, she recognized the importance of building systems, developing support teams and investing in business operations rather than appearances. For women managing multiple ventures, sustainable growth often begins with strengthening existing businesses instead of immediately pursuing another income stream.
7. Redefine What Financial Freedom Means to You
For Washington, financial success has evolved beyond luxury purchases and impressive earnings. As a single mother, her priorities increasingly center on creating stability, building systems and developing opportunities that can benefit future generations.
“Wealth means freedom,” Washington shared, describing her desire to build businesses that create long-term financial independence without requiring constant hands-on work.
That philosophy also shapes Manifesting Millions, her developing book project exploring entrepreneurship, ambition and the strategies behind financial success.
Building a Stronger Financial Future in 2027
As women entrepreneurs prepare for another year of possibilities, Washington’s journey demonstrates that financial literacy is just as important as ambition. Understanding credit, planning for taxes, managing debt and establishing reliable business systems can create a stronger foundation for sustainable growth.
Her experience also reinforces an important truth: Financial mistakes don’t have to define an entrepreneur’s future. With greater awareness, accountability and intentional planning, business owners can make decisions that better support their long-term goals.
The goal for 2027 shouldn’t simply be making more money. It should be building the financial knowledge, stability and freedom to make that success last.
Follow Nicole Washington on social media@nicole_themogul_
